Markets: stock, volume, corridors
To understand the European swap-body market, you need three data points at once: the absolute fleet size, the volume of KV traffic in which they circulate, and the corridor networks that carry that traffic. Only the combination paints the picture of an industry that has grown steadily for three decades and enters a new cycle in 2026.
Stock: 250,000 to 400,000 units in Europe
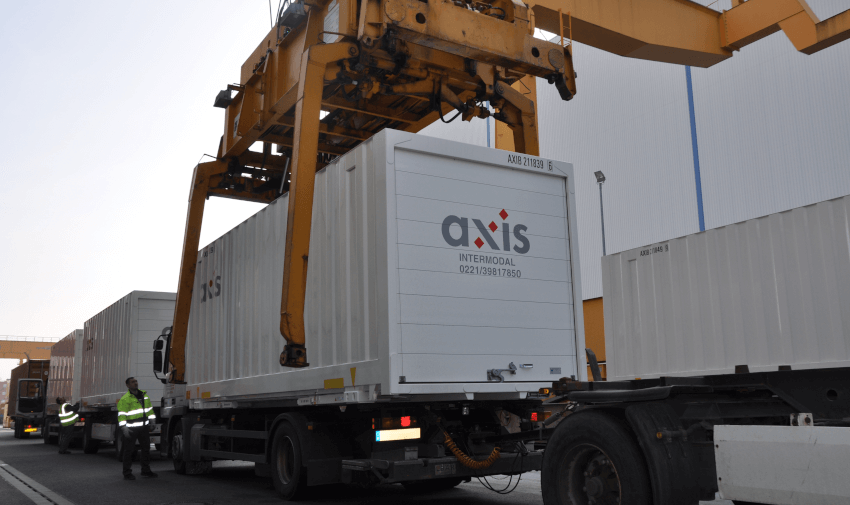
According to estimates by the major lessors and operators, the European swap-body fleet sits between 250,000 and 400,000 units. The spread arises because, depending on methodology, different categories are counted: active KV bodies, pure road units, storage and reserve bodies, and older inventory still used as static storage rooms.
Three commercial pools dominate the rental segment; alongside them, a long tail of smaller providers and forwarder-owned fleets. Germany is by far the largest single market — estimates put the stock at between 90,000 and 130,000 units, driven by the dense industrial network, DB's KV corridor structure and BMDV funding. Poland has grown strongly in KV — modernisation of the rail network and Gdańsk hinterland connections have produced significant fleet expansion over the past decade.
Corridor network and volume
European KV volume is reported annually by UIRR and Eurostat. Key corridors for swap-body deployment:
- Hamburg–Milan (north-south main corridor) — highest volume, multiple daily trains, industrial inbound in northern Italy.
- Rotterdam–Warsaw (port hinterland) — high-growth corridor connecting Polish e-commerce distribution.
- Antwerp–Halle (lorry-rail) — junction for the Belgian-German industrial axis.
- Cologne–Verona — main artery for southern German groupage to Italy.
- Hamburg–Munich / Hamburg–Nuremberg — domestic parcel/express and groupage corridor.
On these main lines, multiple direct trains run daily with 30 to 36 KV wagons each — that means 60 to 72 swap bodies per train. A single body can run two to three line-hauls per week on such a corridor, depending on hub dwell time, pre-/post-haulage and utilisation.
Growth drivers 2026
1. Toll + ETS 2 + KV funding act in parallel
The German lorry toll was extended in December 2023 with a CO₂ component; for Euro-6 vehicles, increases up to 83 percent are documented depending on axle count. From 2027, ETS 2 extends the EU emissions trading scheme to road transport, with a further CO₂ price on diesel haulage. In parallel, BMDV KV funding continues — both levers shift the economic threshold towards rail.
2. CSRD reporting forces shippers towards rail
Industrial shippers must, from financial year 2024/25, report Scope 3 emissions in audit-grade form. The most reliable reduction path is a higher rail share — and at scale that only works via crane-handleable swap bodies. The asset class becomes structurally demanded as ESG instrument, driven not by ideology but by reporting obligation.
3. Parcel/express seasonality grows more volatile
The German parcel/express sector again handled over four billion shipments in 2024. Growth has flattened, but seasonality is rising — Black Friday, Singles' Day, pre-Christmas concentrate ever more volume in narrow time windows. Pooling models for swap bodies become economically more attractive than pure own fleets, because they absorb peaks without financing 8 to 9 months of overcapacity.
More: Axis Insights #1 — Market briefing 2026 · Asset class for investors · Regulatory framework